
This is the second post in Certum Group's seven-part series bringing our Trade Secret Litigation Playbook to the blog. It draws on Part II of the Playbook, Trade Secret Law in Plain English. Read or download the full Playbook here . Here is a statistic that surprises most executives: in federal trade secret cases that reach a verdict, plaintiffs win roughly 84% of the time. 1 That is dramatically better than the plaintiff win rate in commercial litigation generally. It does not mean every case is easy — the cases strong enough to reach a jury are a selected group — but it tells you something important about what happens when a well-built trade secret claim gets in front of a fact-finder: courts tend to enforce the rights the statute was designed to protect. So why do good claims still fail? Usually not at trial. They fail earlier, on assumptions the claim holder never stopped to test. In more than a decade of evaluating these matters, the same handful of misconceptions come up again and again. Here are six worth clearing up before they cost you a case. Myth 1: "It's only a trade secret if we stamped it CONFIDENTIAL." Marking helps, but it is not required. What matters is whether your overall secrecy program is reasonable under the circumstances — a holistic look at contractual, physical, and technical controls. A perfect stamp on an otherwise open system is worth less than a coherent program with a few gaps. Myth 2: "If part of it is public, none of it is protected." Courts routinely protect a combination of individually public facts when the particular combination delivers competitive advantage. The recipe can be assembled from ingredients anyone can buy. What you protect is the assembly. Myth 3: "Our employees signed NDAs, so we're covered." NDAs are a foundation, not a program. The full set of reasonable measures a serious claim holder is expected to have includes access controls, badging, egress monitoring, exit procedures, and technical segmentation. An NDA in the drawer and nothing behind it is exactly the gap a well-resourced defendant will press on first. Myth 4: "We didn't sue the last person who left, so it's too late now." Trade secret protection is evaluated case by case. Declining to act on one departure does not forfeit your rights as to the next one. Every matter stands on its own facts. Myth 5: "We're too small to enforce against a big company." This one gets the economics backwards. A well-funded claim against a large, solvent defendant is often easier to win — and easier to collect — than a disorganized claim against a small one. Resources can be added to a strong case; facts cannot be added to a weak one. The right capital partner exists precisely so that a smaller plaintiff can stand toe-to-toe with a much larger adversary and neutralize the outspend-them tactics that used to decide these fights. Myth 6: "It's just know-how — courts don't protect that." Courts protect integrated know-how constantly. The question is never whether know-how is capable of protection; it is whether you can identify it with enough particularity to describe what was taken. 2 That is the single most consequential early decision in the case, and it is the one most claim holders do not realize they are making when they plead "our proprietary software" instead of the specific, described combinations that actually give them an edge. The through-line Notice what these myths have in common: each one leads a claim holder to under-invest in a case that the numbers say is very winnable. The 84% figure is not a promise. It is an invitation to take the early work seriously — the secrecy program, the identification, the evidence — because that work is what turns a strong set of facts into a strong case. Get those right, and the law is on your side more often than in almost any other kind of commercial dispute. Go deeper with the Playbook. This post covers one piece of a much larger picture. For the full framework — what the law requires, what a strong pre-filing case looks like, how damages experts value these matters, how counsel fee structures change your economics, and how litigation finance fits in — read Certum Group's Trade Secret Litigation Playbook , our field guide for business owners and the counsel who advise them: certumgroup.com/the-trade-secret-playbook . And if you are evaluating a live dispute — or simply want to pressure-test what a matter is worth and how it might be funded — get in touch. A confidential conversation with Certum is free and carries no obligation, whether or not you ultimately seek funding. Reach us at certumgroup.com/contact-us . Sources 1. Stout, Trends in Trade Secret Litigation (2024), reporting an approximately 84% plaintiff-favorable outcome rate across 271 federal trade secret cases reaching a verdict since 2017. 2. Both the federal Defend Trade Secrets Act (18 U.S.C. Section 1836) and the state Uniform Trade Secrets Act define a trade secret as information that derives independent economic value from not being generally known or readily ascertainable, and that is the subject of reasonable measures to keep it secret.
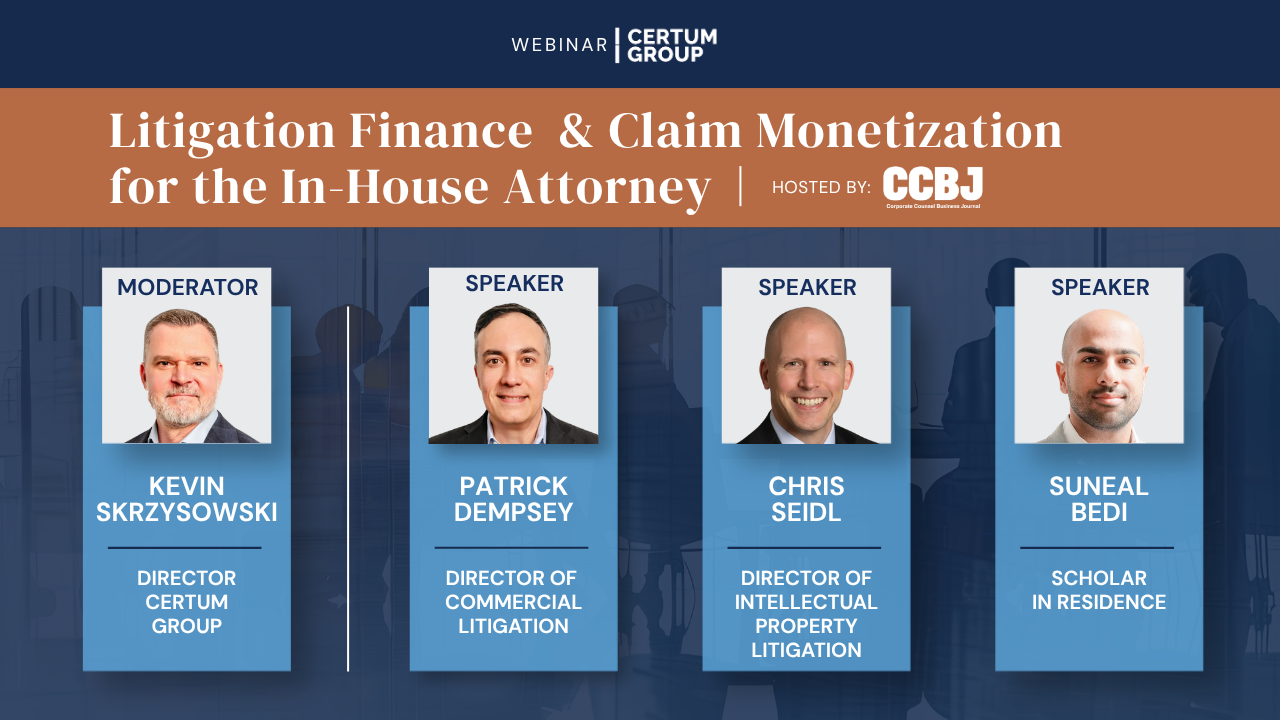
For most companies, the legal department is viewed purely as a cost center—a line item to be managed and minimized. But many organizations are sitting on significant, unrealized value in the form of affirmative claims: lawsuits they could bring against suppliers, vendors, or competitors who have breached a contract, stolen trade secrets, infringed intellectual property, or otherwise caused recoverable damages. All too often these valuable claims go unpursued because litigation is expensive, unpredictable, and competes with the business for budget and headcount. Certum Group, in conjunction with the Corporate Counsel Business Journal, created this one-hour webinar to show in-house counsel how litigation finance changes that calculus— allowing companies to pursue meritorious claims with little or no out-of-pocket cost and on a non-recourse basis, so the downside risk shifts to the funder while the company retains the upside. Our panel brought together leaders in commercial litigation, intellectual property litigation, and legal academia and demystified how litigation finance works and walked through practical, real-world uses for the corporate legal team. We also took a close look at claim monetization: the ability to receive cash today against the value of a pending or contemplated claim, rather than waiting years for a judgment or settlement. Monetization can take the form of an upfront advance secured by the expected recovery, or an outright sale of the claim to a specialized organization that then prosecutes the case and collects the judgment. Attendees left with an understanding of when litigation finance and monetization make sense, how to evaluate and pitch a case, what to expect from the process, and how these tools can transform the legal department from a cost center into a genuine contributor to the bottom line. Watch the full webinar replay HERE . Supporting Materials: Litigation Finance Guide In-House Survey Research Brief Trade Secrets Playbook
This is the first post in Certum Group's seven-part series bringing our Trade Secret Litigation Playbook to the blog. It draws on Part I of the Playbook, Why Trade Secret Claims Matter Now. Read or download the full Playbook here . In 2025, federal trade secret filings reached an all-time high — roughly 1,551 new cases in U.S. district courts, up from 1,203 just two years earlier. 1 That is not a blip, and it is not a quirk of the docket. It is the visible edge of a structural shift in how companies create value and how easily that value now walks out the door. Trade secrets used to be the quiet cousin of the intellectual property family — patents got the valuation multiples, trademarks got the brand meetings. That era is over. For a lot of growth-stage companies, the trade secret portfolio can be worth more than the patents, copyrights, and trademarks combined. It rarely shows up on the balance sheet, and it is almost never insured against the risk it actually faces — which is not that someone will design around it, but that someone will take it. So it is worth understanding why the numbers are climbing, because each driver points to a specific exposure that a business owner can do something about. Employees move more, and faster The single largest source of trade secret disputes is not corporate espionage. It is ordinary talent mobility. Roughly 60% of misappropriation cases involve a departing employee, typically heading to a direct competitor. Tenure has shortened, remote work has normalized discreet cross-company job searches, and the volume of departures that touch sensitive information has grown accordingly. The prototypical case a decade ago was a sales rep leaving with a customer list. Today it is a design lead, a data scientist, or a process engineer carrying the company's hardest-won know-how — sometimes in a file, more often in their head. The cost of taking information has collapsed A USB drive, a personal cloud folder, an auto-forwarded email rule, a screenshot script — what once required filing cabinets and a truck now takes a few minutes. The technical friction that used to deter casual misappropriation is largely gone. That has two consequences. It makes the taking easier, and it makes the forensic trail richer: badge records, git commit histories, egress logs, and download timestamps now tell a story that is often more persuasive to a judge than any witness. The evidence exists. The question is whether the claim holder preserves it before it rolls off a ninety-day retention setting. AI has raised the stakes Machine-learning models are trained on data, code, and process knowledge that is frequently proprietary. Competitors racing to ship an equivalent product have a powerful incentive to shortcut the long, expensive path of independent development — and in software, life sciences, financial services, and advanced manufacturing, a six-to-twelve-month head start can be worth hundreds of millions of dollars. When the crown jewels are unpatented know-how, misappropriation is not a nuisance. It is an existential competitive event. Apple's 2026 trade secret suit against OpenAI — built around aggressive hiring from Apple's hardware teams — is only the most visible example of a pattern now playing out across the economy. A single, credible venue Finally, the law itself has changed the calculus. Since 2016, the federal Defend Trade Secrets Act has given claim holders a nationwide cause of action, federal discovery tools, and remedies strong enough to matter — including an extraordinary ex parte seizure procedure. 2 Enforcement is more predictable than it was under a patchwork of state statutes, and predictability attracts plaintiffs. It also attracts capital, which is where a firm like ours enters the picture. What it means for you From the underwriter's chair, the trend line is unambiguous: more valuable secrets, more mobile employees, cheaper theft, and a legal framework that rewards claim holders who move deliberately. The companies that fare worst are the ones that treated their secrecy program as a compliance checkbox and discover, only in a complaint, that it was the strategy all along. The companies that fare best have thought about identification, preservation, and enforcement economics before they ever need them. If your business runs on information other people would love to have, the record filing numbers are not abstract. They are a forecast. Go deeper with the Playbook. This post covers one piece of a much larger picture. For the full framework — what the law requires, what a strong pre-filing case looks like, how damages experts value these matters, how counsel fee structures change your economics, and how litigation finance fits in — read Certum Group's Trade Secret Litigation Playbook , our field guide for business owners and the counsel who advise them: certumgroup.com/the-trade-secret-playbook . And if you are evaluating a live dispute — or simply want to pressure-test what a matter is worth and how it might be funded — get in touch. A confidential conversation with Certum is free and carries no obligation, whether or not you ultimately seek funding. Reach us at certumgroup.com/contact-us . Sources 1. Lex Machina, Trade Secret Litigation Report (2026), reporting an all-time high in federal trade secret case filings in 2025; see also Lex Machina, Trade Secret Litigation Report (2024) (1,203 federal filings in 2023). 2. Defend Trade Secrets Act of 2016, Pub. L. No. 114-153, 18 U.S.C. Section 1836 et seq.